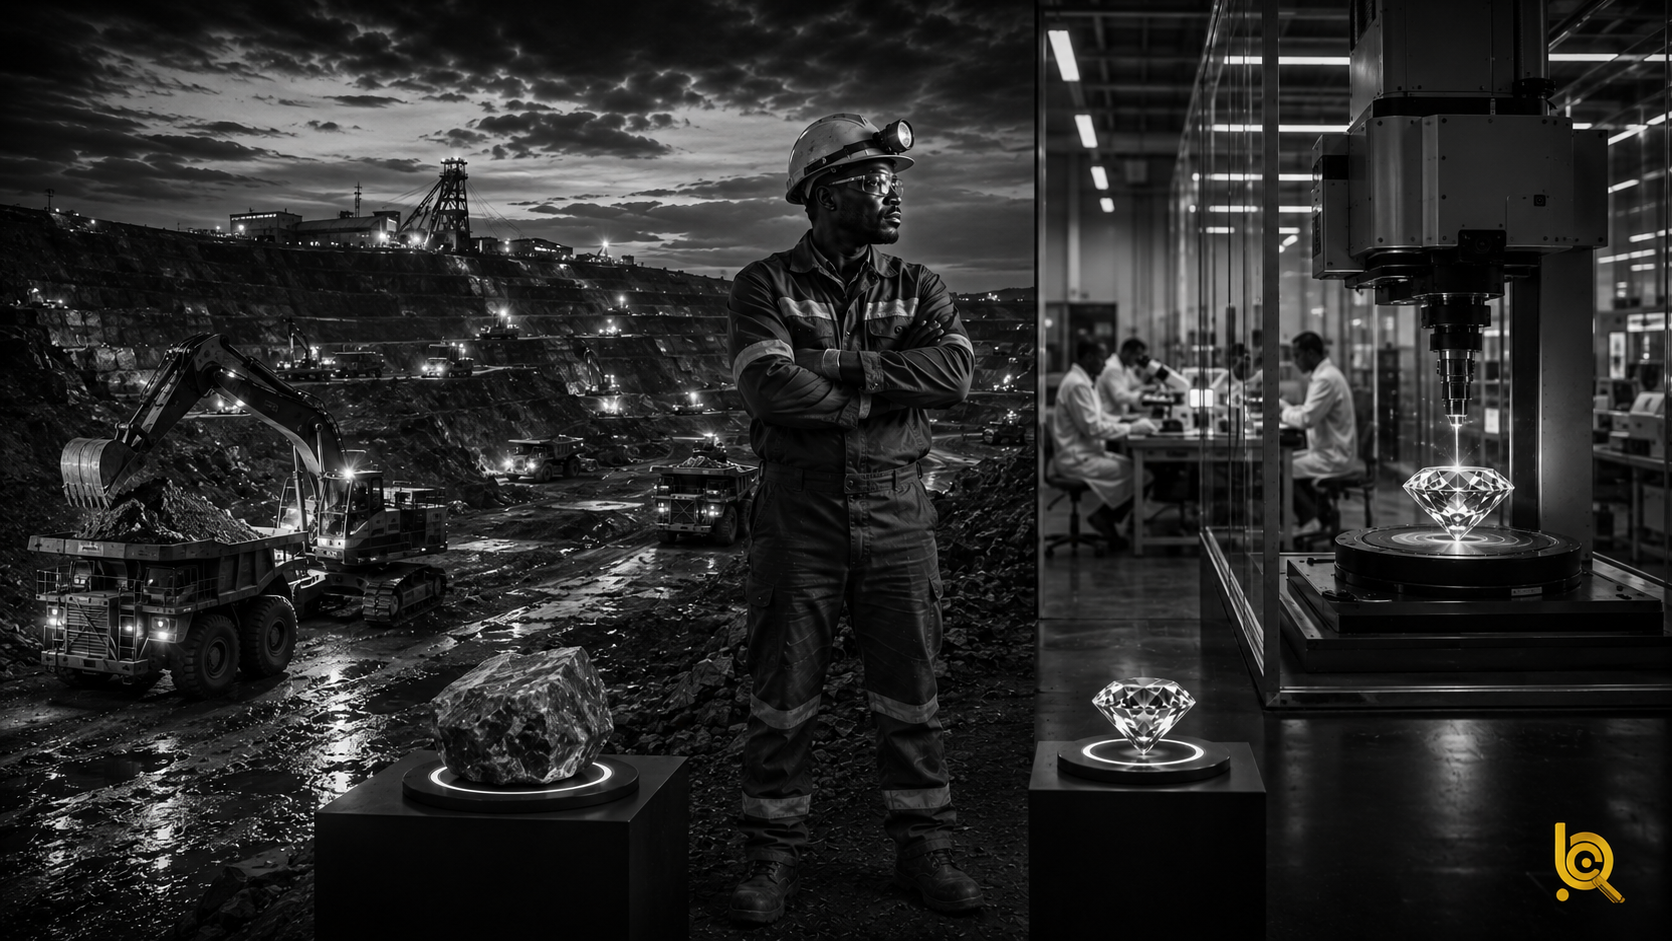
In a laboratory somewhere in China or India, at this moment, a rough diamond is being grown. The process takes between two weeks and three months. The result is a stone that shares the identical crystal structure, hardness, refractive index, and optical properties of a natural diamond — one that gemological laboratories can only distinguish from a mined stone through the sophisticated analysis of growth patterns and microscopic inclusions that no buyer would ever see with the naked eye. And it sells for up to 80 percent less.
This is not a future threat to Botswana’s economy. It is the present one. Lab-grown diamonds, which accounted for around 1 percent of global sales in 2015, now represent nearly half of engagement ring purchases in the United States — the world’s most important diamond market. Natural diamond prices have fallen by roughly 30 percent since their peak in 2022. Botswana is currently sitting on a diamond stockpile estimated at 12 million carats that it cannot sell at acceptable prices. Across clinic queues in Gaborone, construction companies laying off workers, and university students threatening to boycott lectures over unpaid allowances, the effects of this shift in a laboratory abroad are being felt in kitchens and classrooms and bank queues across the country.
How We Got Here
At independence in 1966, Botswana was among the poorest nations on earth. The discovery of diamonds in Orapa in 1967 and subsequently at Jwaneng and Letlhakane transformed the country’s development trajectory in a way that is genuinely remarkable and genuinely rare. Botswana became the world’s top diamond producer by value, and second-largest by volume. Diamond revenue funded schools, roads, hospitals, and a public service that became the de facto employer of the educated middle class. The country was held up globally as proof that a resource-rich African nation could escape the “resource curse” — the pattern of conflict, mismanagement, and stagnation that afflicts so many commodity-dependent states.
Between 2023 and 2025, Debswana’s output dropped by 39 percent. The government forecasts diamond revenue in the fiscal year ending September 2026 at less than half the historical average. The Pula Fund, built over decades as a savings buffer, has been drawn down through successive deficits. Ratings agencies have downgraded the country. The medicine shortage that prompted a national health emergency in August 2025 — with HIV medications, cancer drugs, insulin, and mental health supplies all running critically low simultaneously — was directly connected to the diamond downturn depleting the government’s ability to pay its suppliers.
Botswana did not escape the resource curse. It deferred it. The bill has now arrived — not through conflict or mismanagement, but through a technology invented in a laboratory.
The Lab-Grown Argument and Its Limits
The diamond industry’s response to the lab-grown challenge has centred on differentiation: the rarity argument, the romance argument, the billions-of-years-old argument. De Beers itself — the company whose marketing invented the modern diamond engagement tradition with “A Diamond Is Forever” — launched the Lightbox brand of lab-grown diamonds at a deliberately low price point, a strategy to separate the lab-grown segment from the natural one by commoditising the former.
The strategy has not worked as intended. Hollywood celebrities, Bollywood stars, and a generation of Gen Z social media influencers have embraced lab-grown diamonds specifically because they are cheaper and marketed as conflict-free and eco-friendly. The “rarity” argument struggles when the stones are, in every physical property, identical — and when the consumer buying them knows this. Siddarth Gothi, chairman of the Botswana Diamond Manufacturers Association, has acknowledged that lab-grown stones have “given stiff competition, especially in lower-quality stones,” a category that represents the volume end of the market.
The higher-value, exceptional-quality stones — the kind produced at Jwaneng in particularly large or gem-quality grades — may retain a genuine rarity premium for longer. But the mass market, and with it the pricing floor that gave Botswana’s fiscal model its stability, has fundamentally shifted.
What Diversification Actually Requires
Botswana has known, since at least the early 2000s, that diamond dependence was a structural risk. Vision 2036 — the national development framework adopted before the current crisis — explicitly targets economic diversification as a core objective. The Botswana Economic Transformation Programme, launched in July 2025, reiterates this. Tourism, financial services, digital economy, agro-processing, and renewable energy are all named as alternative pillars. President Boko has spoken of telemedicine, light manufacturing, and unlocking the dynamism of young Batswana through AI.
The problem is not the language of diversification. Botswana has produced excellent language on diversification for twenty years. The problem is that the economy’s diversification credentials, measured in actual GDP contribution by sector, have not moved meaningfully in that time. Tourism contributes an estimated 13 percent of GDP through the Okavango circuit, but total tourism revenue of $393 million in 2023 was still well below pre-pandemic levels of $712 million in 2019, and the sector employs mainly entry-level workers in remote concessions. Financial services are growing, but from a small base. Manufacturing remains a fraction of a percent of exports. Digital services barely register.
The new Sovereign Wealth Fund, launched in September 2025 with Farouk Gumel as board chair and a mandate to invest both domestically and internationally on commercial lines, is a more structurally sound vehicle than the Pula Fund it supplements — ring-fenced, development-focused, governed by the Santiago Principles, and committed to quarterly public reporting. But a fund’s effectiveness is determined by what it invests in, not by its governance structure. The sectors that could employ Botswana’s 2.6 million people at scale do not yet exist at the scale required.
The Old Model Is Gone. What Fills the Void?
The lab-grown diamond is not going away. Its production costs continue to fall. Its quality continues to improve. The potential supply is, unlike mined diamonds, essentially unlimited — constrained only by the electricity and equipment available to the factories producing them, predominantly in China and India. The natural diamond market will survive in some form, almost certainly concentrated in the highest-value, most exceptional stones for the wealthiest buyers. But the mass market that funded Botswana’s development model is gone, and it is not coming back in the form it took between 1970 and 2020. What comes after that model is the most consequential question in Botswana’s economic history since the discovery of diamonds in the Orapa kimberlites. The country has the political will, the institutional stability, and — for now — the time to answer it. Whether the answers being built are at the scale the question demands is what the next five years will reveal.
Sources: Fortune; Al Jazeera; Mining.com; CS Monitor; Daily News Botswana; S&P Global Ratings; Botswana Diamond Manufacturers Association; Bank of Botswana; PACT Africa; Bloomberg.